


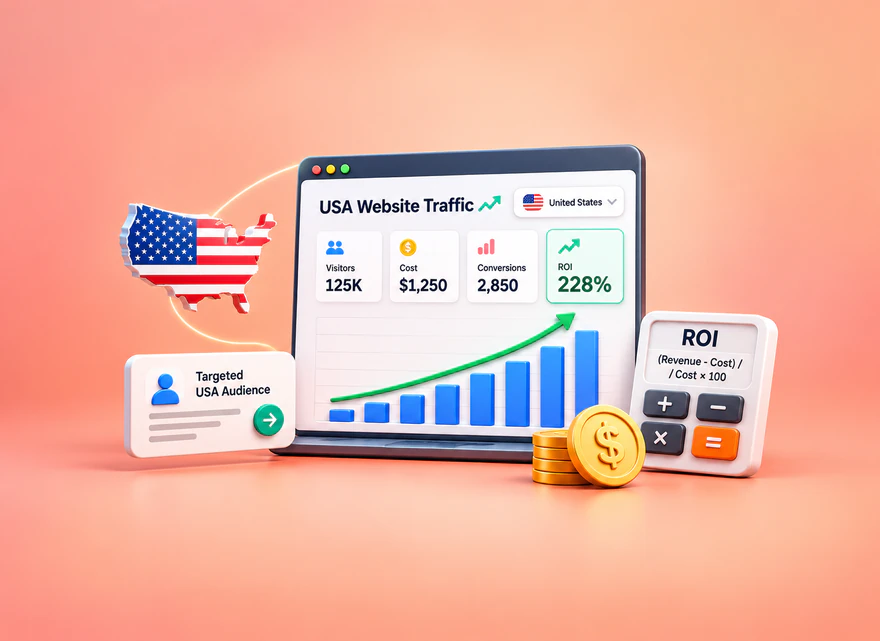
Calculate whether a USA-targeted website traffic campaign covers its full acquisition cost. Compare ROI with ROAS, follow a hypothetical margin and break-even example, and use verified outcomes to decide whether to stop, revise or continue.
To calculate ROI for a USA website traffic campaign, subtract the cost of fulfilling the resulting sales and the full campaign cost from the revenue credited to that campaign. Then divide the remaining contribution by the campaign cost. More visits or a positive revenue report do not necessarily mean the campaign made money.
This guide shows how to build that calculation, find the break-even point and decide whether to stop, revise or cautiously continue a US-targeted campaign. It keeps delivered visits, recorded sessions, qualified actions and verified sales separate. The numerical example is explicitly hypothetical, not an SEOVisitor performance claim or an expected return.
How to calculate ROI for a USA website traffic campaign
First define what you mean by ROI. This article uses campaign ROI on acquisition spend: the return left after order-related variable costs and campaign-specific acquisition costs, divided by those acquisition costs. It is a campaign decision measure, not your company’s final net profit or a universal accounting definition.
Contribution before campaign cost = net campaign-attributed revenue − order-related variable costs. Net revenue should reflect discounts and refunds, while variable costs can include goods, payment fees and fulfillment. Do not subtract the same adjustment in both places.
Campaign ROI = (contribution before campaign cost − full campaign cost) ÷ full campaign cost × 100. Full campaign cost includes the traffic purchase plus relevant setup, creative, measurement and management costs. Keep that denominator consistent across comparisons. Google’s ROI explanation also accounts for production costs, but its total-cost example uses a different denominator; do not compare percentages without checking the formula.
For example, $1,200 of net sales minus $720 of order-related costs leaves $480 to cover acquisition. If the campaign costs $600, the result is −$120 and ROI is −20%. When analytics assigns credit, call this attributed ROI. Calling it incremental ROI requires evidence that the campaign created sales that would not otherwise have happened.
Increase USA Traffic
If you’re looking to buy USA website traffic, SEOVisitor lets you create a country-targeted campaign for the page you want to promote and track the resulting visits.
Before ordering, write down the contribution you need to recover and the maximum amount you are willing to risk on learning. Country targeting narrows a delivery setting; it does not establish purchasing intent. Treat the service description as the campaign specification and your reconciled business records as the evidence of economic value.
Put the destination page, offer, delivery dates, approved spend and measurement owner in a short campaign brief. State whether the decision concerns a first test or a repeat campaign, because reusable setup work changes the cost comparison. Keep a copy of the original assumptions with the eventual results. If the offer or budget changes during delivery, record when it changed rather than presenting the whole period as one unchanged test.
Confirm the US offer before testing the budget
A country setting is useful only when the destination can serve that audience. Complete these checks before entering a revenue assumption in the worksheet; an unavailable offer can make a neatly calculated break-even target irrelevant.
- Offer availability: confirm the US locations you can actually ship to or serve. Record exclusions and any inventory or appointment limits.
- Price and currency: use one reporting currency, normally USD for this example, and state how exchange charges or conversions enter the ledger.
- Fulfillment and refunds: include the relevant shipping subsidy, payment fees, returns and service effort. Use the actual offer’s costs rather than a business-wide average that hides US-specific expenses.
- Destination and completion: verify the selected page, mobile enquiry or checkout path, and the business record that confirms a useful outcome.
- Measurement agreement: retain the provider’s delivery count alongside GA4 sessions. Give the campaign a consistent label without assuming the two counts will match.
- Review boundary: name the spend cap, delivery period, reporting time zone, outcome-maturation date and person responsible for reconciliation.
If a prerequisite fails, resolve it before interpreting a weak return as a targeting problem. For broader landing-page preparation, use a dedicated readiness guide; this calculation concerns the economics of one defined US-targeted test.
ROI, ROAS and traffic cost answer different questions
ROAS measures attributed revenue divided by advertising or traffic spend. It does not automatically deduct goods, servicing or campaign setup costs. A campaign can have revenue several times its media spend and still lose money. ROI adds the economic costs that a revenue multiple leaves out.
In the example above, $1,200 revenue divided by the $500 traffic package is 2.4× ROAS. Including the $100 setup cost changes the revenue-to-acquisition-cost ratio to 2×. Neither ratio is the −20% margin-based campaign ROI. Label each measure rather than presenting one as proof of the others.
Cost per delivered visit describes delivery economics. Cost per qualified lead or verified order describes acquisition efficiency. Neither becomes customer acquisition cost unless the denominator genuinely counts new customers and the numerator includes the acquisition costs you say it includes. Repeat orders and multiple orders from one customer need separate treatment.
If your decision is which channel to fund rather than whether this particular test recovered its cost, use our comparison of SEO ROI and paid advertising ROI. Keep the time horizon, margin definition and cost boundary consistent before comparing its alternatives with the USA campaign calculation below.
Build a full cost ledger without double-counting
Use a simple ledger before launch. Separate costs that vary with sales from costs of acquiring those sales, and state the review period and currency. This makes a later decision reproducible instead of dependent on whichever dashboard number looks most encouraging.
Give each ledger entry an amount, supporting record, date, cost category and responsible owner. Mark whether it is a cash payment or an allocation of internal time, and whether it belongs to this test alone or is shared with other work. Establish the allocation rule before comparing channels. A shared design expense cannot be counted in full against one campaign and ignored for another merely because the second result looks better.
| Item | Where to account for it | Common error |
|---|---|---|
| Discounts, refunds and cancellations | Reconciled net revenue; record any unrecovered costs separately | Using gross checkout totals or subtracting refunds twice |
| Goods, payment fees, packing and shipping subsidy | Order-related variable costs | Treating the full sale price as profit |
| Traffic package and nonrecoverable purchase fees | Campaign acquisition cost | Comparing package prices while ignoring final charges |
| Campaign-specific setup, creative and measurement | Campaign acquisition cost, with an allocation rule | Calling a test profitable before setup costs are recovered |
| Sales follow-up and additional support | Relevant servicing or campaign cost, once | Ignoring staff time spent on unqualified enquiries |
| Shared overhead and reusable assets | Disclosed allocation or separate sensitivity view | Changing the allocation to make one channel look better |
Do not count sales tax collected for remittance as business earnings. Likewise, distinguish a shipping charge collected from the actual shipping cost. Use the same treatment throughout the sheet. If different currencies are involved, use one documented conversion basis rather than mixing invoice amounts with converted revenue.
One-time work deserves two views when appropriate: the first test including setup, and a possible repeat test using genuinely reusable assets. Do not erase the first loss by assuming unlimited future campaigns. Separate cash expenditure from allocated internal time so a decision-maker understands both the cash risk and the resources consumed.
Keep a dated version of each review. If an order is later refunded, update the net revenue and any genuinely unrecovered costs in the relevant campaign cohort. Retain the earlier provisional view so the reason for the change is visible. This is more informative than quietly replacing the reported ROI with a new percentage while leaving the underlying order count unexplained.
For wider consequences of poor-fit visits, see the related cost analysis. Here, keep the ledger limited to defensible amounts and disclose uncertainties rather than inventing a financial value for every inconvenience.
An opportunity cost can inform the choice between campaigns without becoming a second invoice in ROI. If the same team could run an email campaign instead, compare the alternatives using consistent costs, time horizons and qualified outcomes.
Compare the expected contribution in dollars as well as the percentage. A high ratio from a very small test may contribute less to the business than a modest ratio from a larger, repeatable campaign. Neither figure settles the decision alone: consider the resources committed and how dependable the underlying evidence is. Keep the same cost boundary across alternatives, and show pending outcomes separately instead of comparing one settled campaign with another campaign’s optimistic forecast.
A hypothetical USA traffic campaign: from visits to margin
Entirely hypothetical scenario: a store that ships within the United States tests one product landing page during a defined campaign period. It spends $500 on traffic and $100 on dedicated setup and measurement. These are invented amounts for arithmetic, not current SEOVisitor prices or a forecast of its service.
The provider reports 800 delivered visits. GA4 records 720 campaign-labelled sessions and 35 sessions with a useful product or cart action. After the stated purchase-delay and refund review, eight distinct, verified orders are credited to the campaign. Net revenue is $1,200 and associated variable costs are $720. The example assumes one order per purchasing session and settled adjustments solely to keep the calculation understandable.
Copyable ROI worksheet: transfer the fields below to your own sheet or review document and fill the final column from campaign invoices, analytics and reconciled order records. The example column uses the same hypothetical test described above. Blank fields are intentional; they are not zeroes, and this is a worksheet rather than an automatic calculator.
| Field and calculation | Hypothetical example | Your test |
|---|---|---|
| Traffic purchase, including applicable purchase charges | $500 | ________ |
| Other acquisition costs: setup, creative, measurement and relevant management | $100 | ________ |
| Full acquisition cost: sum the two cost inputs | $600 | ________ |
| Provider-delivered visits | 800 | ________ |
| Recorded campaign sessions in GA4 | 720 | ________ |
| Sessions with the defined useful action | 35 | ________ |
| Verified, attributed orders after the stated review | 8 | ________ |
| Reconciled net revenue | $1,200 | ________ |
| Associated order-related variable costs | $720 | ________ |
| Contribution: net revenue − variable costs | $480 | ________ |
| Campaign result: contribution − acquisition cost | −$120 | ________ |
| Acquisition-spend ROI: result ÷ acquisition cost × 100 | −20% | ________ |
| Acquisition cost per order: acquisition cost ÷ verified orders | $75 | ________ |
| Average contribution per order: contribution ÷ verified orders | $60 | ________ |
| Break-even total orders: round acquisition cost ÷ contribution per order up | 10 | ________ |
| Orders remaining to break even: max(0, break-even total − verified orders) | 2 | ________ |
Attach the campaign URL, date range, currency, cost policy and outcome status to the completed sheet. Delivered visits, recorded sessions and useful actions describe different stages; only verified business outcomes supply the revenue input. The eight orders produce $480 of contribution against $600 of acquisition cost, so the decision is still a $120 loss rather than a profitable campaign with eight sales.
Handle missing or zero inputs explicitly. With no verified orders, cost per order and observed contribution per order are undefined; report the spend and unresolved outcomes instead of dividing by zero. With no acquisition cost, this ROI denominator is undefined. If contribution per order is zero or negative, there is no positive finite break-even order target under this model. The break-even estimate assumes the stated margin and fixed campaign cost; it does not predict that additional orders will arrive without additional spending.
The arithmetic is ($480 − $600) ÷ $600 × 100 = −20%. Acquisition cost per attributed order is $75, while contribution per order is only $60. Buying more of the same visits is not justified merely because the revenue report shows sales or ROAS exceeds 1×.
The difference between 800 delivered visits and 720 recorded sessions needs investigation, not an automatic fraud accusation or a silent substitution. Collection settings, consent, session definitions and the provider’s delivery method can affect the comparison. Preserve both counts and investigate the measurement before drawing a conclusion about audience quality.
Calculate break-even orders and test the assumptions
For a simplified one-product campaign with stable costs, divide full campaign cost by contribution per order. Round up to a whole order when the result is fractional. This estimates the total orders needed to recover acquisition spend, not a promised conversion rate.
In the hypothetical example, $600 ÷ $60 = 10 total orders. The campaign has eight, so it needs two more orders at the same contribution and no extra campaign cost to break even. It does not need ten additional orders. At the assumed $150 net revenue per order and 40% contribution rate, break-even net revenue is $1,500.
Using the example’s 720 recorded sessions, eight purchasing sessions represent about 1.11%; ten would represent about 1.39%. Those are arithmetic descriptions of this invented test, not a “good USA conversion rate.” Do not divide analytics purchases by delivered visits and call the result a GA4 session conversion metric.
Run a downside check. If returns or shipping costs reduce contribution per order to $45, $600 requires at least 14 orders. If margin is zero or negative before acquisition, more orders will not solve the basic unit-economics problem. Correct the offer or cost assumptions before allocating another traffic budget.
For a mixed product range, do not apply one attractive product’s margin to every order. Calculate contribution for the actual basket mix, including relevant discounts and fulfillment costs. If that mix changes, the average contribution per order changes too, so the original break-even order count may no longer apply. Where a dependable average is unavailable, sum the contribution from individual verified orders against campaign cost. This keeps a shift toward low-margin products from being mistaken for an improvement merely because order volume increased.
Small samples remain uncertain even when the arithmetic is exact. A handful of orders is not evidence that the next campaign will reproduce the same rate. Report the outcome alongside the number of valid orders, the measurement window and unresolved adjustments rather than presenting a single ROI percentage as a stable forecast.
Track the campaign in GA4 and reconcile it with real records
Set up measurement before spending. Keep one campaign definition across the provider’s delivery report, analytics and your order or lead records. This section provides the minimum economic measurement workflow; it is not a replacement for a complete analytics implementation.
Use consistent campaign labels and the right reporting scope
Where supported, use a distinct campaign URL with consistent source, medium, campaign name and ID. Test that redirects and the landing page preserve the parameters. Google’s manual-tagging guidance explains how these values populate acquisition dimensions. Do not label purchased visits as organic or invent a source identity to improve the appearance of a report.
For current campaign sessions, review session-scoped acquisition data and the intended landing page. Google’s User acquisition versus Traffic acquisition guide explains why First user source and Session source answer different questions. A customer’s original discovery channel is not necessarily the channel associated with the session under review.
Validate valuable events, not just activity
Test a successful purchase or enquiry and check it in the appropriate reports before launch. For ecommerce, verify the purchase payload, including value, currency, transaction ID and item data, against Google’s revenue-data guidance. A price displayed on screen is not proof that purchase revenue was collected correctly.
Use a unique, non-personal transaction ID for each order. Google’s transaction-ID documentation explains web purchase deduplication. Still reconcile analytics with your payment and order system: repeated events, cancellations, test orders and refunds must not become additional customers or profit.
Bring campaign cost into the calculation explicitly
GA4 does not automatically know an external traffic invoice, your product margin or sales-team effort. Maintain a reconciled cost ledger. If you use campaign data import, match source, medium and date consistently and provide the required cost currency. Imported advertising cost still does not calculate every business expense for you.
Use the same currency, reporting window and outcome definitions when combining reports. Note time-zone differences and delayed purchases. A missing event is a measurement limitation to investigate, not permission to fill the gap with estimated sales.
Keep Google Search Console organic queries and clicks in a separate review. Recorded paid activity does not establish improved organic rankings, faster indexing or additional search demand. Configured visit duration or extra pageviews can affect engagement measurements without demonstrating genuine buyer intent.
Keep an audit trail connecting the campaign label, reporting period, order cohort and cost ledger. Use appropriately protected business records to investigate discrepancies; do not put customer contact details into campaign URLs. If a session total changes after a tagging correction, explain that measurement change separately from the economic result. Better reporting can improve confidence in the calculation without creating an additional sale or recovering money already spent.
Distinguish attributed return from incremental profit
Attribution assigns credit under a reporting method. Incrementality asks what would have happened without the campaign. A returning customer may click a campaign link and complete an order they already intended to place; the attributed contribution is real revenue, but the campaign may not have created all of it.
Where feasible, use a deliberately designed holdout or controlled comparison that avoids overlapping exposure and accounts for normal purchase delay. A simple before/after chart is weaker evidence because promotions, inventory, seasonality and other marketing can change at the same time. Do not call a comparison causal just because it contains a control column.
When a credible experiment is unavailable, show a sensitivity analysis with disclosed assumptions about credited orders rather than claiming measured lift. For example, reducing the contribution credited to a campaign shows how fragile the decision is. Such a range is a planning exercise, not a statistical confidence interval or proof of the true incremental result.
Use a sensitivity check to see how crediting fewer sales changes the decision. The following extension of the same hypothetical example keeps the full $600 acquisition cost in both rows. Only the share of contribution credited to additional business changes.
| Assumption | Contribution credited | Result and acquisition-spend ROI |
|---|---|---|
| All attributed contribution credited | $480 | −$120; −20% |
| 80% credited to additional business | $480 × 80% = $384 | −$216; −36% |
The 80% is an invented assumption, not a measured incrementality estimate. Both rows remain unprofitable under their stated assumptions. This comparison illustrates sensitivity; it cannot determine how much of the campaign’s attributed contribution was genuinely additional.
For lead generation and subscriptions, use defensible value
A form submission is not a closed deal. Define a qualified lead using criteria your business can verify, then follow the cohort through sales acceptance and closed outcomes. Include the cost of contacting and serving those leads. Remove duplicates and test submissions without counting a lead and its eventual sale as two separate sources of revenue.
If the sales cycle has not finished, report spend, qualified leads and pending opportunities. An estimate based on an observed close rate and contribution per customer can support planning, but label it expected value rather than realized ROI. Do not assign the same optimistic revenue amount to every enquiry.
For subscriptions, state a margin horizon and use observed retention, refunds and servicing costs. Do not insert an aspirational lifetime value merely to turn a negative first-month result positive. A campaign can look attractive over a long assumed horizon while creating a near-term cash shortfall the business cannot afford.
Decide whether to stop, revise or continue
Agree on a spend cap, review date, outcome definition and acceptable downside before launch. The appropriate budget depends on your margin, cash capacity and learning objective; there is no universal amount or number of visits that makes a USA traffic test reliable.
Separate an operational check from an economic review. A broken destination or missing purchase event needs attention immediately; a sale that is still within its normal completion or return period needs a clearly marked provisional status. Waiting for outcomes does not require authorizing more delivery. Keep the existing spend cap in force while the cohort matures, and approve any follow-up as a new, bounded decision rather than an automatic extension.
| Observation | Decision | Evidence needed next |
|---|---|---|
| Broken destination, invalid tracking or unavailable US offer | Pause new delivery and investigate | A valid completion path and verified measurement |
| Spend cap reached; reconciled contribution below cost | Stop the current setup rather than automatically extend it | A specific, testable reason a revised campaign may differ |
| Outcomes still pending within a normal sales cycle | Wait for the agreed review; do not scale on provisional revenue | Closed orders, lead outcomes and settled adjustments |
| Positive attributed ROI but fragile assumptions | Keep any follow-up bounded | More reliable margin and incrementality evidence |
| Repeatable contribution exceeds cost under conservative assumptions | Consider a cautious increase, not a guaranteed rollout | Marginal return and capacity at the next budget level |
In the hypothetical −20% scenario, the current setup should not be scaled. Investigate a concrete hypothesis, such as an unavailable offer or an incorrectly credited order cohort, before approving another test. Change only what is needed to test that hypothesis and define a new budget cap.
A positive historical average is not enough to justify extra spending. Review the contribution produced by the additional budget: marginal acquisition can be unprofitable even when earlier results were strong. Capacity, customer service and delivery costs may also change as sales grow.
Keep the final report compact: campaign definition, period, delivery count, recorded sessions, qualified actions, verified revenue, variable costs, acquisition costs, attributed ROI, uncertainty and next decision. Record who owns the follow-up and which result would change the decision.
Make the USA traffic decision on economics, not promises
The existing USA website traffic service describes current delivery and configuration choices. Review those terms separately from this educational calculation. Country targeting alone does not guarantee identity, purchase intent, sales or return, and a purchased visit does not become organic search growth because of its source label.
A useful test has a defined offer, a limited financial exposure and an honest measurement plan. Recovering acquisition cost is a minimum hurdle, not proof of a sustainable business. Continue only when reconciled margin and the strength of the evidence justify the next spend; otherwise stop, learn and allocate resources elsewhere.
If you are still seeking a new website’s first US customers, distinguish an acquisition test from evidence of customer demand before committing more budget.
Frequently Asked Questions
Quick answers to common questions about ROI for USA website traffic campaigns
For the acquisition-spend measure used here, subtract order-related variable costs from net attributed revenue, subtract full campaign acquisition cost, then divide by that acquisition cost and multiply by 100. Disclose the formula and attribution uncertainty.
Revenue does not show what remains after goods, payment fees, fulfillment and campaign costs. A campaign can record sales or positive ROAS while losing money; reconcile net revenue and contribution before judging profitability.
Use supported campaign tagging, review session-scoped GA4 acquisition data and validate purchases or qualified enquiries. Reconcile those outcomes with business records, refunds and a separate cost ledger; analytics does not automatically know your full costs.
Pause for broken pages or unreliable tracking. Stop at the agreed spend limit when defensible contribution does not cover cost. Consider a bounded follow-up only when reconciled outcomes, uncertainty and expected marginal return justify it.
No. Geography targeting and delivered visits do not guarantee buyer intent, conversion or organic ranking gains. Evaluate the paid campaign separately from Search Console organic performance.
ROAS divides attributed revenue by advertising or traffic spend. The campaign ROI calculation in this guide also deducts order-related costs and full acquisition costs, so positive ROAS can coexist with negative ROI.
Divide full campaign acquisition cost by contribution per order and round up where necessary. At $600 campaign cost and $60 contribution per order, ten total orders break even; with eight recorded, two more are needed under the same assumptions.
Include campaign-specific setup and relevant staff effort under a disclosed cost policy. Separate cash payments from allocated time and explain shared costs. Keep the same boundary across comparisons; a repeat campaign using reusable assets should not erase the first test's setup cost.
No. A provider's delivery count and GA4's recorded sessions use different definitions and collection methods. Preserve both counts, investigate discrepancies and use the correct denominator for each metric. Neither count alone establishes verified customers or profitable sales.
Mark unsettled outcomes as provisional and use a stated review window suited to the purchase cycle. Reconcile refunds and unrecovered costs with the relevant order cohort, preserving dated versions of the calculation. Do not report pending opportunities as realized profit.
Not necessarily. Cost per order counts orders, while customer acquisition cost should count genuinely new customers and the acquisition costs included in your definition. Several orders from one person or orders from returning customers do not represent the same number of newly acquired customers.

Comments
Leave a Comment